For many Canadian farm families, succession does not always mean transferring the farm to a son or daughter. Sometimes the family member who wants to continue farming is a niece, nephew, or another member of the extended family.
Budget 2026 proposes an important change that recognizes this reality. Beginning with transfers occurring on or after January 1, 2027, the federal government proposes to significantly expand the intergenerational farm property rollover.
How Do the Current Farm Rollover Rules Work?
Under the Income Tax Act, qualifying farm property can currently be transferred to a taxpayer's child, or the child's spouse or common-law partner, on a tax-deferred basis. For these rules, a "child" also includes a grandchild or great-grandchild.
This can be extremely valuable for farm succession. Without a rollover, transferring appreciated farmland or other qualifying property can generally result in a capital gain based on the property's fair market value.
The rollover allows some or all of that capital gain to instead be deferred, helping families transition the farm without necessarily creating a significant immediate tax bill. Importantly, this is a deferral of tax, not necessarily an elimination of the gain.
What's Changing in 2027?
Budget 2026 proposes expanding the rules to allow qualifying transfers to a:
- Niece or nephew;
- Niece or nephew of the farmer's spouse or common-law partner;
- Spouse or common-law partner of an eligible niece or nephew; or
- Child of an eligible niece or nephew.
In practical terms, this means the rollover can extend to grandnieces and grandnephews as well. The proposed legislation would apply to transfers occurring after 2026.
Why This Matters for Alberta Farm Families
This is a meaningful change for family farms.
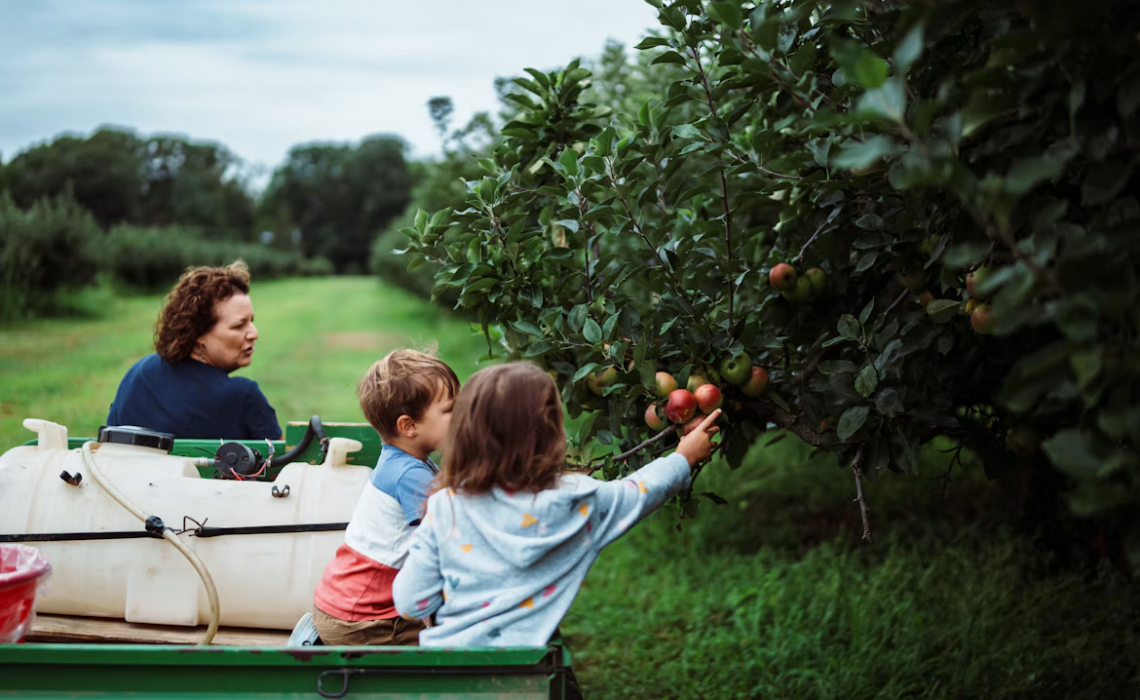
Consider an Alberta farmer whose children have pursued careers outside agriculture, while a nephew has spent years working on the farm and intends to take over the operation. Under the existing rules, transferring the farm to that nephew does not receive the same rollover treatment as transferring it to a child or grandchild.
Starting in 2027, that could change.
The proposal provides families with considerably more flexibility to transition a farm to the family member who actually intends to continue the operation, rather than having the tax rules influence who should receive it.
The Rollover Isn't Automatic
The expanded definition of family does not mean every transfer of farmland to a niece or nephew will automatically qualify.
The existing rollover rules contain requirements regarding both the type of property and its historical farming use. Property that may qualify includes farm real estate, shares of certain family farm corporations, and interests in family farm partnerships, provided the applicable conditions are satisfied.
There can also be significant differences between structuring a transfer as a rollover and triggering a gain intentionally to make use of available capital gains deductions.
For this reason, succession planning should generally happen before the farm is transferred, not after.
What Should Farm Families Do Now?
If your farm's likely successor is a niece, nephew, grandniece or grandnephew, 2027 may present a new succession-planning opportunity.
Before completing a transfer, consider reviewing:
- Who will ultimately take over the farming operation;
- Whether the land, corporate shares or partnership interests qualify for the rollover;
- The property's adjusted cost base and current market value;
- Available capital gains deductions;
- Whether a complete rollover or intentional realization of some capital gain makes the most sense; and
- How the tax plan fits with your will and overall estate plan.
The proposed changes take effect for transfers occurring on or after January 1, 2027, so the timing of a planned transfer can be particularly important.
Final Thoughts
Farm succession is about more than tax. The objective is to transition the farm to the people who are best positioned to carry it forward.
Budget 2026's proposed expansion of the farm rollover rules provides significantly more flexibility for families where that person happens to be a niece or nephew rather than a child or grandchild.
If you're considering transitioning your farm in the next few years, JMH & Co. can help review the tax implications and develop a succession plan before the transfer takes place.
This article is based on proposals contained in the November 5, 2026 federal budget and accompanying draft legislation. The rules may change as the legislation proceeds through Parliament.
This blog was written by Katelynne Devine.
Want to make sure it all adds up? Connect with us!
At JMH & Co., we are your partner for financial success.
Book an appointment with us or give us a call today.
Medicine Hat (403) 527-4451
Brooks (403) 362-4004
Calgary (403) 261-0835